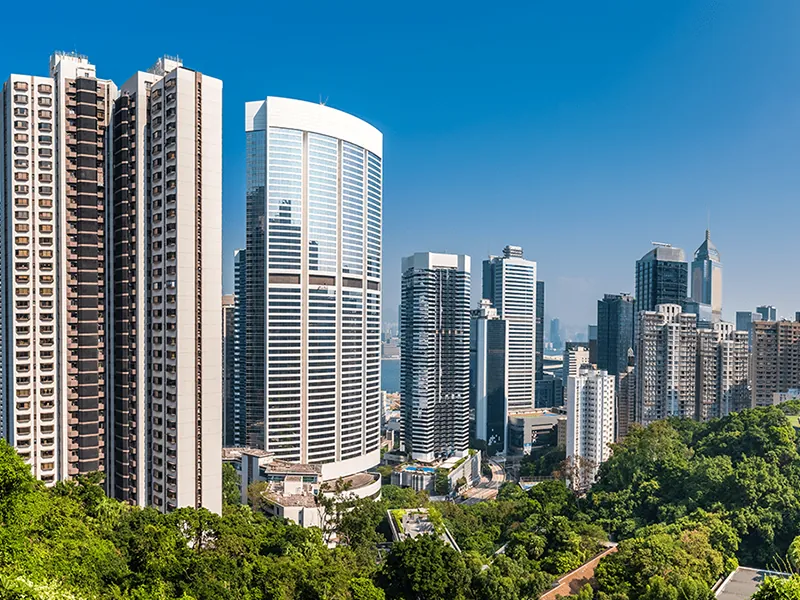
The challenge is that no single factor explains this shift. Affordability continues to influence residential purchasing decisions. Infrastructure is opening up new locations, while premiumisation is changing what buyers and occupiers are willing to pay for. At the same time, economic activity remains critical to determining whether demand in a location can be sustained beyond an initial wave of interest.
INTRODUCTION
Office absorption across leading markets reached 26.9 million sq ft in H1 2026, an 11.6% year-on-year increase, according to JLL. Housing sales across Bengaluru, Mumbai, Pune, Delhi NCR, Hyderabad, Chennai and Kolkata grew 8% in Q1 2026, while retail leasing rose 10.5% in the first half of the year. At the same time, premium housing continued to take a larger share of residential sales.These trends point to a real estate market that is growing, but not uniformly. Different asset classes are responding to different economic forces, and even within the same segment, demand is becoming more discerning. For 2027, the question is therefore not simply where demand will grow, but what is driving that demand, whether it is supported by underlying economic activity, and how developers and investors can distinguish sustainable opportunities from short-term expectations.
This makes affordability, infrastructure and premiumisation three important lenses to examine the next phase of India's real estate growth.
Affordability is about value, not just price
Affordability will remain important, particularly in residential real estate, even as premium housing continues to perform well. In Q1 2026, sales of homes priced above INR 10 million in the top seven cities increased 30%, while sales below INR 10 million declined 24%. The premium segment accounted for about 71% of sales, compared with 59% a year earlier.This does not mean the broader market has stopped being price-sensitive. It suggests that buyers who have the purchasing capacity are willing to spend more when the location, size, quality and overall proposition justify the price. For a large section of the market, however, the monthly cost of ownership continues to matter. This is why affordability is being defined as value for money rather than simply a lower ticket price.
A buyer may be willing to move slightly farther from a central location if a new metro line or road provides reliable connectivity and allows them to get a larger home within their budget. Similarly, an office occupier may accept a higher rent for a better-quality building if the location improves employee access, workplace efficiency and retention.
The same logic applies to retail and logistics. A retailer needs occupancy costs to make sense against expected sales, while a logistics operator will compare land and warehouse costs with the savings generated through better supply-chain efficiency. For developers, the market will reward projects that offer a convincing balance between cost and utility.
Infrastructure will decide where growth happens
Infrastructure has always influenced real estate, but its role is becoming more visible as development expands beyond established urban centres. Metro networks, highways, airports and improved urban transport can change the economics of a location. Better connectivity can make peripheral residential markets viable, bring new office districts within commuting distance, improve retail catchments and open up industrial and warehousing corridors.The logistics sector is a good example. India’s warehousing stock reached around 610 million sq ft in 2025, with demand supported by manufacturing, e-commerce, organised retail and third-party logistics. Industrial and warehousing demand across Bengaluru, Chennai, Delhi NCR, Hyderabad, Kolkata, Mumbai, Pune and Ahmedabad reached about 22 million sq ft in H1 2026, up 12% year-on-year.
For the real estate industry, the more important point is what happens around this infrastructure. A road by itself does not create a sustainable real estate market. It becomes meaningful when it connects people to employment, businesses to markets and producers to consumers.
This will also create opportunities for emerging urban centres. As highways, airports, metro systems and digital infrastructure improve, some Tier-II and peripheral markets will become more attractive to both businesses and residents. However, infrastructure should not be viewed as a guarantee of future appreciation. The strongest locations will be those where connectivity is accompanied by jobs, population growth, commercial activity and social infrastructure.
Premiumisation is spreading across asset classes
Premiumisation is often associated with luxury housing, but the trend is much broader. In residential areas, buyers are looking for larger spaces, better locations, improved design and amenities. In office real estate, the preference is shifting towards Grade-A buildings that provide better technology, sustainability features, employee facilities and operating efficiency.Retail is undergoing a similar change. Consumers are not visiting organised retail destinations only to purchase products. Food, entertainment and experiences are becoming an important part of the proposition. Even logistics is moving up the quality curve. Modern facilities in strategic locations can command greater value because they help occupiers reduce delivery times, improve inventory management and operate more efficiently. This is essentially a flight to quality across real estate.
The important distinction for 2027 will be between genuine premiumisation and simply charging a premium price. A higher-priced home must offer better space, design or location. A premium office must deliver a better working environment. A retail destination needs the footfall and experience to support its tenants. A logistics facility must offer measurable operational advantages. Premiumisation will work where the user can see the value.
Retail and hospitality will follow economic activity
Retail and hospitality provide another reminder that real estate ultimately follows economic activity. Retail leasing across Bengaluru, Mumbai, Pune, Delhi NCR, Hyderabad, Chennai and Kolkata reached 6.27 million sq ft in H1 2026, up 10.5% year-on-year. Domestic retailers accounted for the majority of leasing, with fashion, food and beverage and entertainment among the key categories. Retail performance, however, depends on more than available space. It depends on the catchment, spending power and frequency of visits. Infrastructure can improve access, but the surrounding economy determines whether that footfall can be sustained.Hotel investment in India reached $567 million across 28 transactions in 2025, a 67% increase from 2024. The growing role of Tier-II and Tier-III markets is also significant because business travel, leisure and destination-led tourism are creating demand beyond the traditional metropolitan markets.
A new office hub can create demand for hotels and restaurants. A manufacturing cluster can support business travel and employee housing. A tourism destination can support hospitality, retail and residential development. Looking at these assets individually can therefore miss the larger opportunity.
KEY BUSINESS LESSONS
The market is likely to remain positive, but it will also become more discerning. Before entering a new market, developers and investors will need to understand the source of demand. Is it employment growth, manufacturing, consumption, tourism, digital infrastructure or a combination of these?The next consideration is connectivity. Is the infrastructure already operational, or is the investment dependent on a project that is still several years away? More importantly, does that infrastructure connect the location to an economic centre? The final consideration is the asset itself. Does it provide something that users genuinely value? That could be affordability, accessibility, quality, efficiency, experience or a combination of these. This approach can help separate sustainable growth from markets driven mainly by expectations.
CONCLUSION
Affordability, infrastructure and premiumisation can’t be considered as competing forces in 2027. They will influence different parts of the same market. Affordability will determine how deep demand can go, infrastructure will influence where that demand develops and premiumisation will determine how much value quality assets can command. Economic activity will connect all three, and that is where the sector has a larger opportunity in 2027.The next phase of growth will not simply be about building more. It will be about understanding why demand exists, how different asset classes feed into one another, and whether the economic activity behind a location is strong enough to sustain that demand over time. The markets that bring together connectivity, economic activity and quality are likely to be the ones that stand out.